CHRISTIAN MONEY MINDSET • GRATITUDE & STEWARDSHIP
Enough for Today: Gratitude, Hope, and Christian Money Wisdom
A hopeful outlook cannot control the economy or promise prosperity. It can help you notice what is true, name what matters, and take one wise financial step at a time.
Hello, good morning—let’s begin with another blessed piece of content.
What if a more hopeful financial life begins not with pretending you already have more, but with seeing today clearly? The way we speak to ourselves can shape what we notice and how we respond. Yet an encouraging mindset is not a supernatural shortcut: thoughts alone cannot make income appear, erase debt, guarantee a promotion, or control the markets. Christian hope is more durable than a promise of instant prosperity. It makes room for honest facts, gratitude, wise work, practical planning, and help from other people.
Many households carry an inner script about money. It may say, “There is never enough,” “People like me cannot get ahead,” or “If I were more faithful, this would be easier.” Those sentences can grow out of real strain—low wages, a job loss, caregiving, medical costs, debt, or years of uncertainty. The answer is not to shame ourselves for feeling afraid. The answer is to ask what the fear is telling us, what it cannot know about the future, and what faithful next step is available now.
This guide connects a hopeful outlook with the everyday practice of Christian stewardship. It is for families in the United States and Canada who want to handle money with clarity, compassion, and purpose—without treating wealth as proof of God’s favor or financial hardship as a personal moral failure.
Key takeaways
- A mindset can influence attention and habits, but it does not guarantee financial outcomes.
- Gratitude can coexist with grief, ambition, debt, and the need for assistance.
- Replace sweeping predictions with specific facts, questions, and next steps.
- Stewardship means managing real resources in light of responsibilities and values.
- Small, repeatable actions are more useful than grand promises or self-blame.
1. Let hope face reality
There is a difference between hope and denial. Denial says, “If I do not look at the overdue bill, it cannot hurt me.” Hope says, “The bill is real, and I can learn what choices I have.” Denial tries to protect us by hiding information. Hope helps us remain present long enough to make a decision.
In Scripture, wisdom is often practical: listen, seek understanding, plan carefully, and act with integrity. Proverbs 21:5 praises diligent planning while warning against haste. That is not a promise that every plan succeeds; it is an invitation to pair intention with care. A hopeful person can acknowledge that money is tight, ask for clear terms, and still believe that today’s difficulty is not the whole story of a life.
If you are facing an urgent crisis—food insecurity, a shutoff notice, unsafe housing, or threats from a collector—positive self-talk is not a replacement for help. Contact relevant local services, a nonprofit counselor, a trusted community organization, or a qualified professional. Seeking help is an act of responsibility, not a failure of faith.
2. Notice your money language without condemning yourself
Listen for repeated phrases. “I am terrible with money.” “We will always be behind.” “I deserve this purchase because everything else is hard.” These thoughts may feel like facts, but they often combine an emotion, a past experience, and a forecast. Naming that mixture gives you a little room to choose a response.
Try a three-column note: the thought, the evidence you actually have, and a more accurate replacement. For example: “We can never save” might become “We have not saved consistently this year, and our budget has had little margin. We can review one expense and decide whether even a small amount is possible.” The revised sentence is not artificially cheerful. It is specific, honest, and open to action.
There may be no immediate answer. That is okay. A more precise question—“Which bills are due before the next paycheck?”—is easier to work with than “Why does money always go wrong?” Accurate language does not fix every external problem, but it can stop a painful prediction from becoming the only plan available.
3. Replace magical thinking with faithful agency
Popular prosperity language sometimes says that if you imagine abundance strongly enough, the world must deliver it. That claim can sound empowering, but it may burden people with responsibility for events they cannot control. A family cannot think its way out of a recession, set its own wages, prevent every illness, or guarantee an investment result.
Christian faith does not require us to pretend we command outcomes. It calls us to faithful agency: making the choices that are within reach while staying humble about what is not. You can apply for a better role, build a skill, ask a lender a clear question, set up a modest transfer to savings, or say no to a risky offer. You can also face the fact that some outcomes depend on employers, public policy, health, family needs, and chance.
This distinction protects both faith and sound judgment. Confidence may help you make a phone call you have been avoiding. It cannot make an unsuitable loan affordable. Hope may encourage you to prepare for a goal. It cannot tell you which investment will rise. Let conviction support wise action, not override evidence.
4. Practice gratitude that does not silence need
Gratitude is sometimes presented as a command to be cheerful about everything. That is not a humane or useful approach. You can appreciate a friend’s support and still feel anxious about rent. You can thank God for work while recognizing that the pay is not meeting the household’s needs. You can celebrate a child’s joy while grieving a financial choice that did not work out.
A balanced practice is to write two lines: “What is supporting us today?” and “What needs attention?” Support might include a reliable neighbor, a skill, a church meal, a safe place to sleep, or an upcoming paycheck. The need might be groceries, debt, childcare, or a conversation with a utility company. Neither line cancels the other. Seeing both can keep gratitude from turning into denial and concern from turning into hopelessness.
Gratitude also does not obligate anyone to give money they need for basic commitments. Christian generosity is meaningful when it is thoughtful and freely chosen. It is not a transaction intended to force God to return a larger amount. If a giving decision puts essential needs at risk, pause and seek wise counsel rather than acting from fear, guilt, or pressure.
5. Define abundance by purpose, not comparison
Online images show selected moments, not complete household finances. A home, holiday, car, or business may be financed by debt, family support, years of saving, or circumstances you do not know. Comparing your full life with a stranger’s edited highlight reel can make responsible decisions feel small and ordinary needs feel like evidence of failure.
Instead, ask what a good financial life is meant to support in your current season. For one household, the urgent purpose may be stable housing. For another, it may be caring for an aging parent, reducing high-interest debt, or creating a little breathing room. A family with young children may need flexibility; someone nearing retirement may prioritize predictability. Values can be shared while the practical plan differs.
Write three priorities in order. Then test a purchase, new commitment, or opportunity against them. Does it help support those priorities? What would it displace? Is the cost clear? Is there time to think? Purpose gives money direction. It does not guarantee that every choice will work, but it helps you decide what deserves attention first.
6. Learn the numbers you can influence
Uncertainty grows when basic information stays hidden. A simple household snapshot can replace some guesswork with facts. List take-home income, essential expenses, minimum debt payments, current savings, and predictable irregular costs such as insurance premiums, school supplies, car maintenance, or annual fees. Use recent statements and receipts where available. Estimates are fine for a first pass; refine them as you learn.
Do not make the exercise a trial of your character. The purpose is to understand the system your household is navigating. If the numbers do not balance, that may point to an income gap or high fixed costs—not a failure to buy the right coffee. Record what you learn, identify one question, and choose one next step. That step may be asking about a payment arrangement or looking for local support.
Our Christian budgeting guide explains how to build a spending plan around real priorities. The Money North Money Plan can organize a basic educational snapshot in your browser. Do not enter bank credentials or sensitive account details into a planning worksheet. Use the tool as a starting point, not a personalized recommendation.
7. Make a plan that fits the household you have
A useful plan starts from actual income and obligations rather than from an idealized lifestyle. Begin with essentials and minimum required payments. Then look at flexible spending, upcoming expenses, savings goals, giving, and debt repayment. If money is left over, decide intentionally where it should go. If there is a shortfall, the plan has still done its job: it has made the gap visible so you can consider options sooner.
Choose a review rhythm that your household can sustain. Some families check once a week; others review each payday or monthly. Keep it brief. Ask what changed, what is coming, and whether the plan still reflects the family’s priorities. When multiple people share financial decisions, agree on what needs a conversation before the next large purchase or commitment.
For couples, try to discuss one problem at a time. “We need to fix everything” can invite blame. “Can we look at the grocery spending and upcoming school costs this Sunday?” is more manageable. If money conversations become unsafe or coercive, prioritize safety and seek confidential support. Financial communication should not be used to control or threaten a family member.
8. Build margin in steps, not through shame
Margin is the space between income and expenses that lets a household absorb change. It may be small or nonexistent for a period. When possible, a starter emergency reserve can keep an ordinary repair from turning into new high-interest debt. There is no single correct first target for every family: income, dependents, job stability, insurance, and local costs all matter.
If saving is possible, select an amount that does not cause missed essentials or late fees. A small automatic transfer can create consistency, but automation is optional and should be checked when income changes. If there is no room to save today, focus first on understanding the shortfall and seeking available support. Do not take on costly debt simply to claim that you have an emergency fund.
Our emergency fund guide discusses practical ways to start and grow a reserve over time. A margin-building habit is not a moral score. It is one tool among many, and progress may pause when life gets expensive.
9. Turn broad goals into one next action
“Be prosperous” is too broad to guide Tuesday afternoon. “Review the credit-card statement and write down the due date, balance, and interest rate” is an action. “Stop worrying” is not a realistic command. “Schedule twenty minutes to check the budget with my spouse” is a step. Smaller actions reduce the distance between a value and a behavior.
Use a simple pattern: name the goal, identify the next action, decide when you will do it, and make the action small enough to begin. If the goal is debt reduction, the first move might be listing every balance rather than immediately changing repayment strategy. If it is home ownership, the first move might be learning about total costs and location-specific requirements, not shopping for a loan.
After acting, notice what happened without exaggerating the result. A phone call may provide information but not an immediate solution. A week of tracking expenses may reveal a pattern, not create a surplus. The value is in learning and choosing the next informed step.
10. Invite wise counsel and community
Money decisions can feel private, but isolation often magnifies pressure. A trusted family member, faith leader, nonprofit credit counselor, or qualified professional may help you see options or ask better questions. Different situations call for different expertise. A tax question belongs with a qualified tax resource; an investment decision may warrant a properly licensed professional; a debt crisis may benefit from reputable nonprofit counseling.
Ask what the person is qualified to do, how they are paid, whether they have a conflict of interest, and what alternatives exist. Be cautious with anyone who guarantees a result, rushes you to sign, demands secrecy, or uses religious authority to pressure you into buying a product or giving money. Wise counsel welcomes questions and explains limits.
Community can also offer nonfinancial help: a meal, childcare, a ride, job leads, or someone to sit with you while you sort paperwork. Receiving practical help does not make you less capable. It can give a household time and stability while it considers its next steps.
11. Treat setbacks as information, not a verdict
A budget may fail because an expense was forgotten, a bill changed, or the estimate was unrealistic. A savings transfer may need to pause after a medical cost. A debt plan may slow when work hours are cut. These events can be discouraging, but they do not reveal your worth or predict every future outcome.
Review what happened. Was the plan too tight? Did an irregular expense need its own category? Was the goal out of step with current income? Is there a new resource or person to contact? Adjusting a plan is not the same as abandoning responsibility. A faithful plan is allowed to respond to the real life it is meant to serve.
If you do not want to reopen a statement or account, ask someone trustworthy to sit beside you. Set a short timer, gather only the documents needed for the first step, and stop when the timer ends if you need to. Bringing a hidden problem into view gradually can be more sustainable than demanding a complete turnaround in one day.
12. Keep generosity connected to freedom and care
Christian stewardship includes generosity, but generosity is not measured only by the size of a gift. Time, hospitality, encouragement, practical skill, and money can all serve neighbors. Financial giving should be thoughtful, voluntary, and made with an understanding of household responsibilities. A church or charity should not promise divine profit in exchange for a contribution.
Consider choosing a giving approach that is clear enough to live with: set a modest amount or percentage when feasible, identify causes that align with your values, and revisit the plan when circumstances change. If you give, record it as part of your budget rather than treating it as invisible. If you need to reduce giving for a season, talk honestly and without self-condemnation.
Generosity can widen our sense of purpose, but it must not be weaponized against people under financial pressure. A healthy community makes room for both giving and receiving. It also respects people who need time to decide and provides transparency about how funds are used.
13. Remember that wealth is not a spiritual report card
Money can provide choices and stability; its presence or absence does not reveal the full condition of a person’s faith. Faithful people experience layoffs, disability, debt, illness, family separation, and economic hardship. Others may accumulate wealth through opportunity, diligent work, inheritance, or circumstances that are not shared by everyone. These realities caution us against simple formulas.
Scripture offers wisdom about diligence, honesty, contentment, generosity, debt, and care for the vulnerable. It does not authorize us to promise that any particular practice will yield a larger bank balance. Prosperity claims can make struggling people feel abandoned and can reward those willing to sell certainty where none exists.
A more grounded question is, “How can I handle the resources and responsibilities I have with integrity today?” That question leaves room for ambition and growth. It also leaves room for limits, grief, public support, and the fact that no household controls every condition shaping its finances.
A seven-day practice for a clearer money mindset
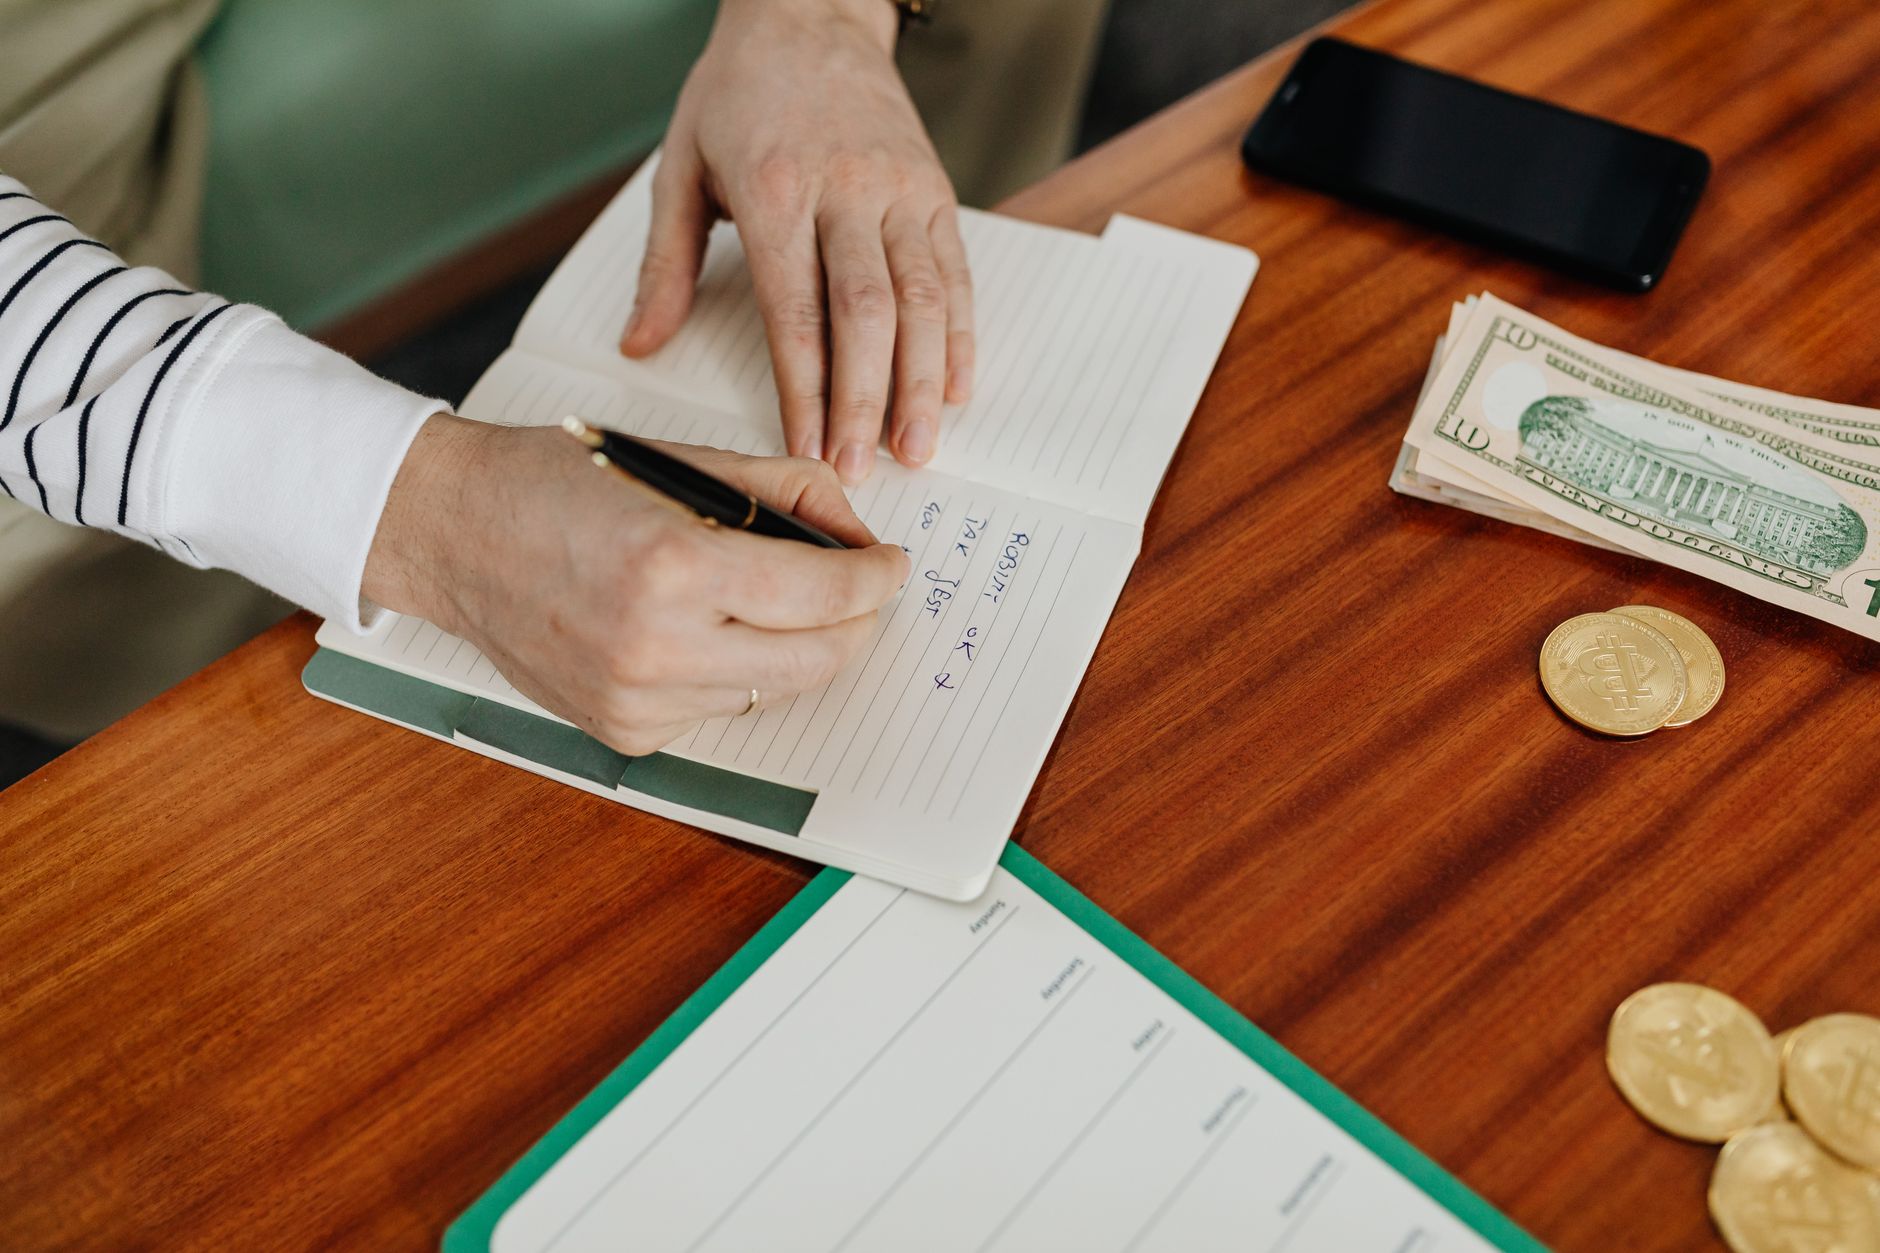
For one week, make a short daily note. Write one fact about your money, one value you want your decisions to reflect, and one question you still need answered. On the first day, list the next bill due. On another day, name an expense that surprised you. Later, notice one resource you appreciate and one cost you may need to plan for. Keep the exercise honest and brief.
At the end of the week, review the notes. Did a fear become more specific? Did you discover a date, balance, or resource you did not have in view? Is there one conversation to schedule or one task to complete? Choose only what is relevant. The aim is not to force an emotional transformation in seven days. It is to build a small practice of attention and follow-through.
If the exercise raises more questions than it answers, that is useful information too. Take the next question to an official resource or qualified professional. For U.S. budgeting support, the Consumer Financial Protection Bureau offers consumer tools. For Canadian households, the Financial Consumer Agency of Canada provides budgeting guidance. Use resources appropriate to your country and circumstances.
Practical next step: a three-line financial reset
Set aside ten quiet minutes today and complete three lines: What is true about my finances right now? What matters most to my household this month? What is one safe, practical next step I can take? If the answer to the first line is unclear, gather the relevant information before making a decision. If the next step feels too large, make it smaller or ask someone trustworthy to help.
For more structure, visit Start Here, use the Financial Tools hub for educational estimates, or read The Power of Inner Conviction for a related discussion of clear thinking and money habits.
Official sources
- Consumer Financial Protection Bureau — Budgeting tools
- Financial Consumer Agency of Canada — Making a budget
- Investor.gov — Introduction to investing
Related reading
Christian Budgeting · Christian Emergency Fund · Biblical Debt Freedom · Wisdom Before Wealth
The Money North Letter
One practical money lesson. One biblical principle. One useful next step. Subscribe by email.
Educational disclaimer: This article provides general financial education and biblical reflection. It is not personalized financial, investment, tax, legal, credit, banking, or insurance advice. Account terms, laws, programs, and consumer protections vary by location and may change.