HOUSEHOLD ECONOMY • SEVEN PRACTICAL PRINCIPLES
King Solomon's 7 Principles for Household Economic Wisdom
Hello, good morning—let’s begin with another blessed piece of content.
A household does not become financially steady because it discovers one secret product, predicts the next market move, or earns a salary large enough to stop paying attention. Stability is usually built through ordinary decisions repeated with honesty: work, planning, restraint, saving, thoughtful risk, and generosity. That pattern sounds modest, but it is remarkably close to the economic wisdom found throughout Proverbs and Ecclesiastes.
King Solomon wrote about fields, merchants, laborers, rulers, lenders, borrowers, inheritance, appetite, and uncertainty. These texts were not modern financial manuals, and we should not force today's products into every verse. Still, they offer durable moral and behavioral principles. They teach us to recognize the danger of haste, the limits of money, the value of foresight, and the responsibility that comes with resources.
This article provides general education and Christian reflection for U.S. readers. It does not provide personalized financial, investment, tax, legal, credit, insurance, or pastoral advice. Investment values can fall, debt terms differ, tax rules change, and household needs are personal. Use current official sources and qualified professionals when a decision depends on your situation.
Principle 1: Contentment protects the household from endless expansion
Ecclesiastes 5 warns that the person who loves money is never finally satisfied by more of it. This is not a condemnation of productive work, prudent saving, or a family improving its circumstances. It is a diagnosis of appetite without a stopping point. If every increase immediately creates a larger lifestyle, greater income may produce greater obligations without producing peace.
Contentment does not mean passivity. It means being able to say, “This is enough for this season,” even when advertising, comparison, and status suggest otherwise. A content household can pursue a better job, education, a home, or retirement without making those goals the measure of human value. It can enjoy good things while keeping the freedom to decline another upgrade.
Practice contentment by defining what “enough” means for a few categories. How much vehicle serves the household's actual transportation needs? How much space can the family maintain without sacrificing every other goal? Which subscriptions are used? What kind of celebration reflects love without creating months of payments? These questions turn contentment into a financial boundary rather than an abstract virtue.
Principle 2: Diligence is more dependable than financial excitement
Proverbs repeatedly contrasts diligent work with neglect and haste. Diligence is not frantic activity. It is careful attention applied over time. In a modern household, it can look like reviewing pay statements, updating a budget, improving employable skills, maintaining equipment, filing documents, checking fees, and completing the next debt payment even when the process feels slow.
Financial excitement often asks for a dramatic answer. It promises that one opportunity, asset, course, or side business will compress years of patient work into weeks. Some opportunities are legitimate, but urgency should never replace verification. Ask how revenue is created, what could go wrong, what the total cost is, whether the seller is licensed when required, and whether you can afford a loss.
A useful rule is to separate learning from buying. Read the disclosure, compare alternatives, and wait long enough for the emotional pressure to decline. If an offer disappears because you asked reasonable questions, it may not have deserved your money. Our purpose-driven wealth guide explores how to resist fast-money pressure without abandoning ambition.
Principle 3: Foresight is a form of protection
Proverbs 22:3 describes the prudent person seeing danger and taking refuge. Financial foresight does not require predicting the exact date of a recession, medical event, or repair. It means recognizing that irregular costs and disruptions are normal parts of life and building reasonable defenses before they arrive.
Begin with a calendar of known nonmonthly expenses: insurance renewals, school costs, vehicle maintenance, annual subscriptions, travel, holidays, taxes, and professional fees. Divide an expected cost by the months remaining and create a sinking fund when the budget allows. A repair is less likely to become a crisis when part of it has already been prepared for.
Then consider risks that cannot be scheduled. An emergency reserve, appropriate insurance, current beneficiary information, and copies of essential documents can reduce confusion. The goal is not to eliminate uncertainty; no household can. The goal is to prevent every disruption from becoming expensive debt or a rushed decision. See our emergency reserve guide for a gradual approach.
Principle 4: Know the state of what has been entrusted to you
Proverbs 27:23 urges careful knowledge of flocks and herds, the productive assets of an agricultural household. The modern application is broader than checking a bank balance. A family needs visibility across income, bills, debt, savings, insurance, taxes, property, and responsibilities to other people.
Create a one-page financial inventory. List checking and savings accounts, debts with interest rates and due dates, recurring obligations, insurance policies, retirement accounts, and major assets. Record where important documents are stored and who should be contacted if the person who normally manages the money is unavailable. Do not place passwords or sensitive account numbers in an unsecured document.
Visibility turns vague anxiety into specific work. “We are bad with money” is too broad to solve. “We have three subscriptions to review, a credit-card balance at a high rate, and no reserve for the annual premium” creates a practical agenda. A monthly household meeting can maintain that visibility without turning every conversation into a crisis.
If you need a starting format, the Consumer Financial Protection Bureau publishes educational tools, including resources for budgeting and managing money. Use official tools as education, then adapt them to the realities of your household.
Principle 5: Borrowing creates obligations that deserve sober attention
Proverbs 22:7 warns about the power relationship between borrower and lender. Borrowing is not automatically a moral failure; homes, education, transportation, or business activity can involve credit. Yet every debt is a claim on future cash flow. The payment remains after the excitement of the purchase has passed.
Before borrowing, compare the annual percentage rate, fees, repayment period, required payment, total estimated cost, collateral, penalties, and consequences of missed payments. Ask whether the purchase can be reduced, delayed, saved for, or obtained another way. Consider how the payment would feel after a drop in income or an increase in essential expenses.
When consumer debt already exists, shame is not a repayment strategy. List the balances, protect required payments, avoid new charges where possible, and direct extra money through a chosen method. The avalanche approach prioritizes higher interest rates; the snowball approach prioritizes smaller balances to create visible progress. Our Christian debt freedom guide explains both without presenting either as a universal prescription.
Principle 6: Build productive capacity, not merely an image of wealth
Proverbs values useful work, skill, land cared for, honest trade, and provision for a household. Productive capacity is anything that helps a family earn, serve, create, maintain, or withstand disruption. It may include education, tools, a reliable vehicle, health, professional credentials, a well-run small business, or long-term investments suitable for the family's goals and risk.
This principle challenges status spending. A depreciating luxury purchase may communicate success while reducing a family's ability to respond to an emergency. A modest tool, certification, or repair may attract little attention while increasing income or preventing a larger cost. Ask what a purchase will enable, what it will require to maintain, and what other goal it will delay.
For long-term goals, investing may help resources participate in productive enterprise, but investing always involves risk. Asset allocation and diversification are not biblical guarantees; they are modern risk-management concepts. Investor.gov explains that an appropriate mix depends on time horizon and risk tolerance, and that even funds may be concentrated. Read disclosures and understand fees before acting.
Principle 7: Wealth should serve responsibility, generosity, and legacy
Biblical wealth is never only private consumption. Resources can support dependents, create honest employment, welcome guests, relieve need, strengthen churches and communities, and prepare the next generation. This purpose gives financial planning a moral center without turning generosity into a promise of financial return.
Generosity should be voluntary, transparent, and sustainable. A household can plan regular giving, maintain a small fund for unexpected needs, and contribute time or skill. It should also evaluate organizations carefully. Ask how funds are used, whether reporting is available, and whether emotional or spiritual pressure is being applied. Faithful causes do not need deceptive methods.
Legacy includes more than assets. Children and heirs need the ability to understand, maintain, and use what they receive. Teach budgeting, work, giving, saving, and the purpose behind family decisions. Keep beneficiary designations and estate documents current with qualified guidance. Our Christian family legacy guide discusses these conversations in greater depth.
Put the seven principles into one household system
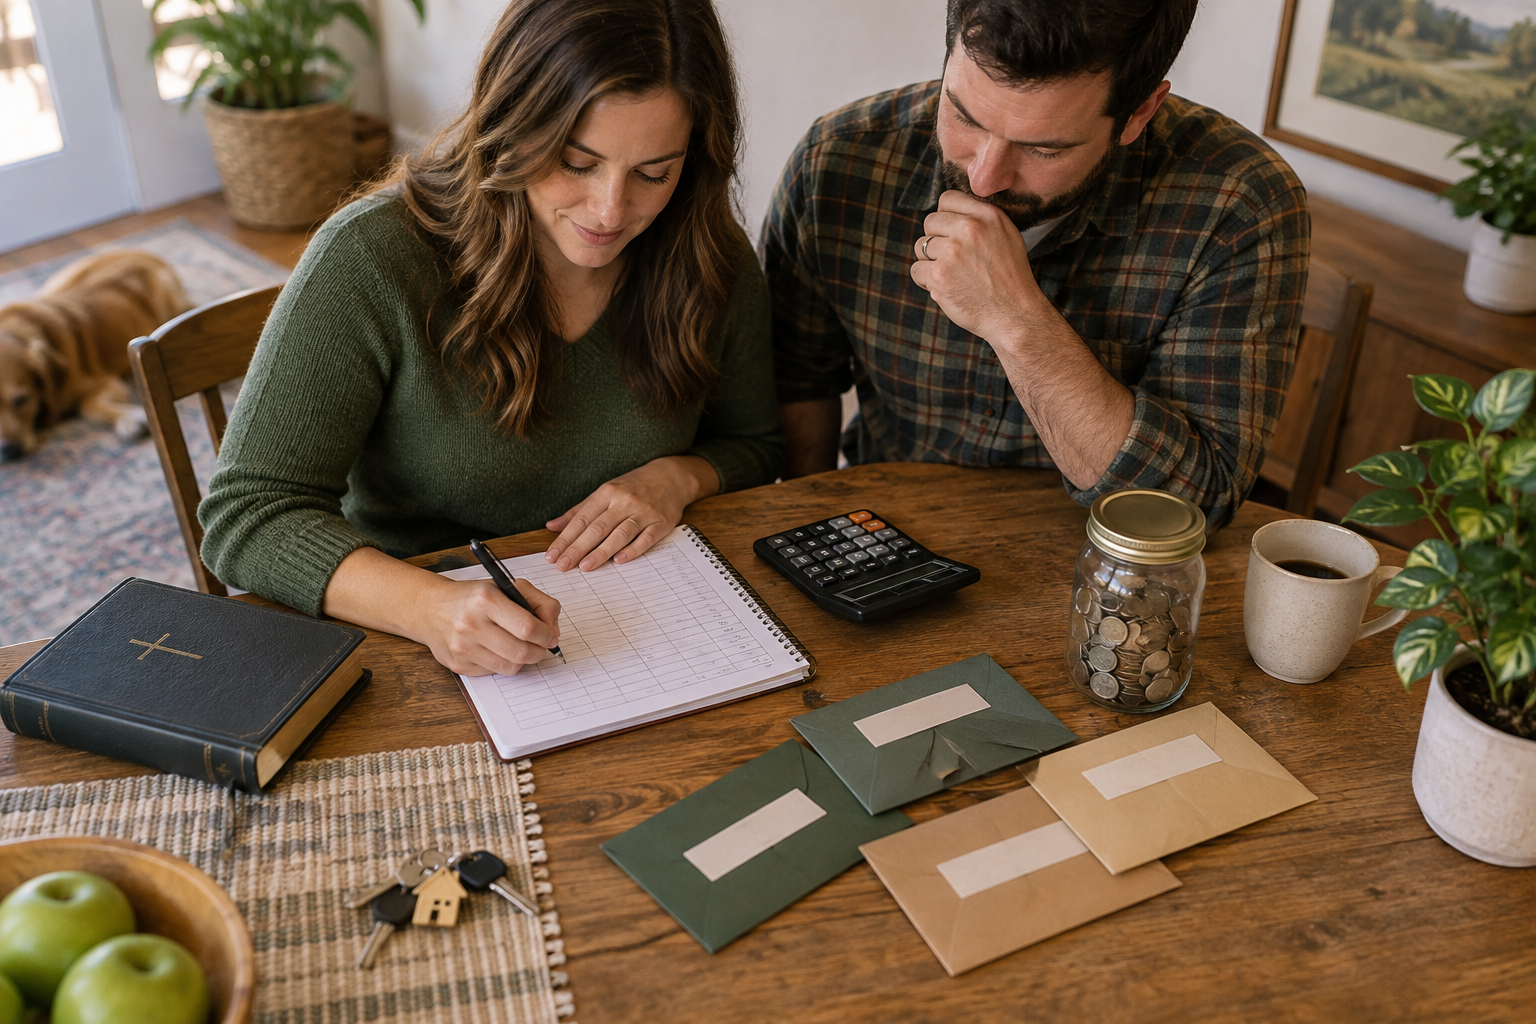
The principles are strongest when they work together. Contentment defines limits. Diligence sustains the plan. Foresight creates protection. Visibility reveals the facts. Caution with debt protects future income. Productive capacity builds usefulness. Purpose directs the result toward people and responsibilities.
Start with a 30-day stewardship review:
- Week one: Track every expense without judgment and list all recurring commitments.
- Week two: Build a simple budget that protects essentials, required payments, giving, and a realistic savings step.
- Week three: Review one major risk—emergency savings, insurance, debt, or an outdated beneficiary—and identify the next action.
- Week four: Hold a calm household meeting, celebrate progress, and choose one adjustment for the next month.
If retirement saving is part of the plan, learn the rules before choosing an account. The IRS 401(k) overview and IRA-based plan information explain basic features. Contribution limits, tax treatment, plan eligibility, employer matching, vesting, fees, and withdrawal rules can change, so confirm current details through official sources and plan documents.
Measure progress without turning net worth into identity
A household needs measurements, but it should choose them carefully. Net worth—assets minus liabilities—can show whether debt is declining and long-term resources are growing. Monthly cash flow can show whether ordinary commitments fit inside actual income. A savings rate, debt balance, emergency reserve, or retirement contribution can help the family see movement that daily account fluctuations might hide.
Yet none of these measurements defines a person's value before God or the community. A negative net worth may reflect student debt, a new mortgage, medical hardship, business loss, or a season of caregiving. A high net worth may conceal strained relationships, dishonest income, concentrated risk, or obligations that are not visible on a statement. Use numbers as instruments for truthful decisions, not as rankings of spiritual maturity.
Choose three or four indicators that fit the current season. A family paying down consumer debt might track total balance, interest charged, on-time payments, and a small reserve. A debt-free household preparing for retirement might track contribution consistency, asset allocation, fees, and whether its plan still matches its time horizon. A small-business owner may need separate personal and business records, cash reserves, tax preparation, and a clear view of receivables and obligations.
Review progress at a regular interval rather than checking every number compulsively. Monthly reviews are useful for cash flow and bills; quarterly or annual reviews may be better for long-term goals. When results disappoint, ask what changed and what can be adjusted. When results improve, practice gratitude without assuming the future is guaranteed. Measurement should support diligence, not anxiety or pride.
Economic wisdom is a practice, not a performance
Solomon's writings do not invite us to display financial superiority. They invite us to become teachable. A wealthy household can be careless and afraid; a modest household can be organized, generous, and resilient. The purpose of these principles is not to compare families but to help each family take the next truthful step.
Choose the principle your household most needs today. Perhaps it is contentment before a purchase, visibility over accounts, patience with debt repayment, or a conversation about legacy. Write the step down, assign a date, and review it with the people affected. Quiet consistency may not look dramatic, but it is one of the strongest financial advantages a family can develop.
Educational disclaimer: The Money North Chronicle provides general educational content and Christian reflection, not financial, investment, tax, legal, credit, insurance, counseling, or pastoral advice. No result is promised or guaranteed. Consider qualified advice for decisions specific to your circumstances.