PROVERBS • WISDOM, ABUNDANCE & STEWARDSHIP
Solomon’s Wisdom: Why Discernment Comes Before Prosperity
Solomon’s story does not offer a shortcut to riches. It offers something more durable: a way to seek understanding before opportunity, so that work, saving, generosity, and growth can serve a life of purpose instead of becoming its master.
Hello, good morning—let’s begin with another blessed piece of content.
Many people want prosperity because they are tired of pressure. They would like room to pay the bills without panic, help people they love, prepare for an uncertain future, and enjoy life without every choice feeling like a crisis. Those desires are understandable. Yet the Bible does not begin its conversation about abundance by promising a particular income, investment return, or lifestyle. It begins with the heart and with wisdom.
Solomon’s story is especially helpful because it contains both extraordinary blessing and an unflinching warning. When God invited the young king to ask for what he wanted, Solomon asked for a discerning heart to govern well (1 Kings 3:5–12). He did not begin by asking for longer life, victory over enemies, or personal wealth. In the story, God gives wisdom and also grants honor and riches. But that sequence matters. Wisdom was not a technique Solomon used to unlock money. It was the gift he valued because people, justice, and responsibility were already in front of him.
For a household today, this is a better starting point than a formula for prosperity. Wisdom helps us see clearly before we sign, spend, borrow, save, give, or chase an opportunity. It helps us distinguish a real need from an anxious impulse, a patient plan from a flashy promise, and a good increase from an increase that quietly costs more than it gives. It cannot guarantee a particular outcome. It can make us more prepared to use whatever outcome arrives with honesty and purpose.
Key takeaways
- Solomon first asked for discernment, not wealth; biblical wisdom begins with responsibility and reverence, not with a demand for results.
- Prosperity in Scripture is broader than a large balance: it can include sufficiency, peace, useful work, relationships, generosity, and the ability to act with integrity.
- Wisdom improves financial decisions by slowing haste, testing claims, counting costs, and keeping long-term responsibilities visible.
- Solomon’s later failures show that abundance does not protect anyone from pride, distraction, or divided loyalties.
- Christian households can seek growth without treating faith as a transaction that guarantees material wealth.
What Solomon actually asked for
First Kings 3 places Solomon at the beginning of a demanding responsibility. He is young, leading a people, and aware that he cannot govern alone by instinct. His request is often translated as an understanding or discerning heart: the ability to distinguish good from evil and to govern justly. In the immediate story, wisdom is not private self-improvement. It is a public responsibility. His decisions would affect families, work, safety, and the nation’s future.
That context rescues the passage from a common misuse. Solomon was not told, “Ask for wisdom and you will always be rich.” Nor is every reader promised the same visible outcome. Instead, Scripture shows a king who recognizes the limits of his own understanding. He asks for the kind of perception that helps him carry responsibility without becoming careless with the lives of others.
That is a powerful prayer for ordinary money decisions. Before a family pursues more income, starts a business, changes jobs, accepts a loan, sells an asset, or makes a major purchase, it can ask for a discerning heart. What facts are we missing? Who will this affect? What obligations will remain after the excitement fades? Does this decision fit our values, energy, and current season? Those are wisdom questions. They do not eliminate risk, but they make room for truth before urgency takes over.
The contrast is important. A person can seek prosperity as a way to avoid ever needing help, ever feeling vulnerable, or ever being told no. Solomon’s early request points in another direction: seek the capacity to serve well. Financial growth is healthiest when it strengthens provision, generosity, useful work, and faithful responsibility rather than merely enlarging a private image of success.
Prosperity is not the same as accumulation
In everyday language, prosperity can mean a large income or growing assets. In the Bible, the idea is richer and more demanding. It includes peace, well-being, fruitful labor, justice, secure relationships, and the ability to live in a way that honors God. A household can have more possessions and less peace. It can gain a higher salary while losing rest, trust, health, or attention to the people closest to it. It can look prosperous from the outside while remaining trapped by debt, secrecy, or constant comparison.
Proverbs speaks positively about diligent work, planning, and provision. It also warns repeatedly against haste, dishonest gain, greed, and the illusion that wealth can answer every question. Proverbs 13:11 contrasts wealth gained hastily with gathering little by little; Proverbs 21:5 commends the plans of the diligent; Proverbs 22:7 warns that borrowing can create a power relationship. These sayings are not a guarantee that diligence will prevent every hardship. They are wise observations about patterns that often protect a household from needless harm.
That distinction protects readers from two damaging messages. The first says that wealth is always suspicious, so faithfulness means refusing ambition or planning. The second says that visible abundance is proof of spiritual maturity, so financial hardship must signal insufficient faith. Scripture does not support either message. Job was righteous and suffered deeply. Boaz was wealthy and used his position to protect Ruth’s dignity. Zacchaeus was rich and needed repentance that changed the direction of his money. The question is never only how much a person has. It is what money is doing in the person and through the person.
1. Wisdom begins by telling the truth about the present
Financial anxiety grows easily when everything remains vague. A household may know that money feels tight without knowing which bill, habit, debt, or upcoming expense is creating the pressure. Wisdom begins with honest sight. In agricultural language, Proverbs 27:23 urges careful knowledge of the state of one’s flocks. A modern household can practice the same care by knowing its income dates, essential bills, debt balances, savings, insurance, and foreseeable annual costs.
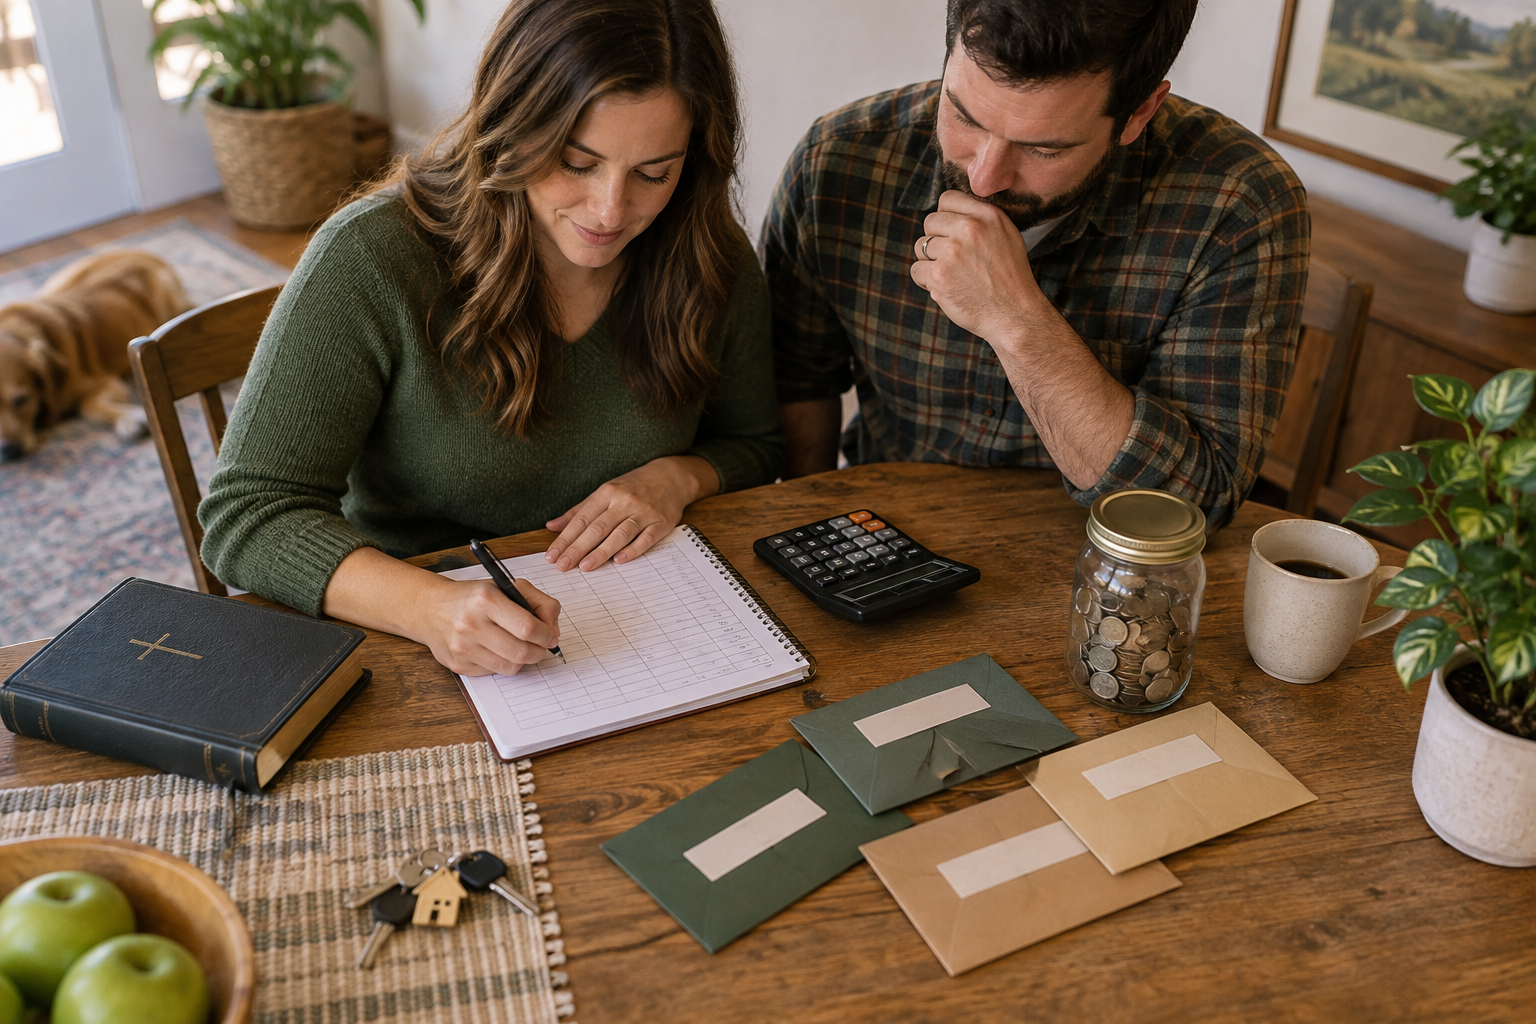
This is not an invitation to obsess over numbers. It is an invitation to replace fog with facts. Make a simple one-page snapshot: cash available, next income date, essential costs, minimum debt payments, current savings, and any predictable expenses due in the next three months. If income varies, use a conservative figure rather than the best possible month. If money is shared, bring the numbers into a calm conversation instead of keeping one person in the dark.
Truth can be uncomfortable at first. It may reveal that small cuts will not solve a large shortfall, that a debt payment needs closer attention, or that a goal must be delayed. But a painful fact is usually more useful than a comforting guess. It makes a next step possible. Our Christian budgeting guide and Money North Money Plan can help organize a general educational snapshot without asking for bank passwords or account credentials.
2. Wisdom slows down the voice of haste
Solomon’s proverbs repeatedly put patience beside diligence because haste can look like progress while producing expensive mistakes. A rushed purchase, a loan signed under pressure, a trend followed because everyone is talking about it, or a business offer that cannot survive basic questions may all promise a faster route to prosperity. But speed is not evidence. A confident salesperson, a polished social-media post, or a countdown timer cannot replace a clear explanation of cost, risk, terms, and alternatives.
Before making a significant financial commitment, create a pause. Ask for the full agreement in writing. Compare more than one option. Calculate the total cost, not only the monthly payment. Ask what happens if income changes or a repair appears. If the decision involves an investment, be cautious of anyone who promises certainty, minimizes risk, pressures you to act immediately, or discourages independent research. For foundational investor education, Investor.gov explains risk, diversification, and common fraud warnings.
Slowing down does not mean missing every opportunity. It means refusing to call pressure “wisdom.” A sound opportunity can bear questions. It can survive one night of sleep, a conversation with a spouse, or a second opinion from someone who is not paid to sell it. If it cannot, the urgency itself has become valuable information.
3. Wisdom makes room before it reaches for more
One practical meaning of abundance is margin: enough room to handle an ordinary surprise without immediately turning to high-cost debt or despair. No amount of margin removes every crisis. But even a modest reserve, a plan for predictable costs, and lower fixed obligations can make a household more resilient. This is why saving is not simply about having a larger number on a statement. It is about protecting choices when life changes.
Start with the foreseeable. Annual insurance renewals, school costs, vehicle maintenance, gifts, travel, taxes, registrations, and subscriptions do not arrive as emergencies simply because they are not monthly. A sinking fund divides an expected cost into smaller amounts over time. That kind of preparation is humble; it admits that life contains recurring needs and that tomorrow’s expense should not always become tomorrow’s debt.
Then build a starter emergency reserve at a pace the household can sustain. The target will differ by employment stability, dependents, housing, health, and existing debt. There is no biblical verse that assigns every family the same number of months. A small first reserve is still meaningful because it creates a new habit: when a surprise occurs, the first response can be a plan rather than panic. Read The School of the Ant or try the educational Emergency Fund Calculator for a simple estimate.
4. Wisdom grows through work that serves real people
Prosperity is often discussed as though it comes from finding the right secret. Proverbs gives a steadier picture: skill, diligence, honesty, and useful work have value. A person can grow their capacity through training, reliability, a well-maintained tool, a fair business practice, thoughtful communication, or simply finishing the work in front of them. These are not glamorous shortcuts, but they are often more durable than a sudden opportunity that no one truly understands.
For some readers, the next wise step may be pursuing a credential, updating a résumé, asking for clearer expectations at work, learning a tool that is relevant to their field, or separating business and household records. For others, it may be rest and recovery after a demanding season. Wisdom takes human limits seriously. It does not glorify overwork or suggest that people who are ill, caregiving, unemployed, disabled, or underpaid have simply failed to work hard enough.
When income increases, pause before spending the whole increase. Ask what needs repair in the household system. Is there a costly debt to reduce, an emergency fund to begin, an insurance question to clarify, a retirement benefit to understand, or a family need that has been postponed? Using every raise to expand lifestyle can leave a family with a bigger salary and the same fragility. Directing part of an increase toward stability can create freedom that lasts longer than a purchase.
5. Wisdom measures the cost of debt honestly
Debt deserves neither denial nor shame. It is an obligation that claims future income, and wisdom asks what that claim will require. A payment that looks manageable in a calm month can become heavy when hours are reduced, a child needs care, rent rises, or a vehicle fails. Before borrowing, compare annual percentage rate, fees, repayment length, penalties, collateral, and the total cost over time. Ask whether the purchase can be reduced, delayed, saved for, or obtained another way.
If consumer debt already exists, begin with reality: list each balance, rate, minimum payment, and due date. Protect essential needs and on-time payments where possible. Then choose a payoff approach you can explain. The debt avalanche emphasizes higher rates; the debt snowball emphasizes smaller balances and visible progress. Neither method is a test of faith. The more important question is whether the plan is truthful, repeatable, and protects the household from adding new debt while trying to repay old debt.
When the situation is serious, ask for trustworthy help. In the United States, the Consumer Financial Protection Bureau provides education about debt collection and consumer rights. Canadian readers can begin with the Financial Consumer Agency of Canada’s debt resources. Rules and programs vary, so verify current details and seek qualified assistance for decisions specific to your circumstances.
6. Wisdom keeps generosity connected to truth
Solomon’s wisdom literature repeatedly turns the reader outward. Prosperity that only enlarges private comfort is incomplete. Money can provide food, shelter, care, employment, hospitality, support for family, and help for neighbors. Giving becomes healthier when it flows from gratitude and conviction rather than pressure, fear, or the promise of a financial return from God.
A wise household can plan generosity in a way that does not conceal its own essential needs. It might set aside a modest recurring amount, support a trustworthy local need, offer a practical skill, share a meal, or help a relative navigate a difficult month. The form differs by season. A family with rent, food, medicine, or safety at risk should not be manipulated into a financial gift that creates a new crisis. Trustworthy ministries and organizations welcome questions about how funds are used and do not threaten people for needing to proceed carefully.
Generosity also requires integrity in how money was made. Zacchaeus’s response to Jesus included restitution. If a household knows that a financial matter has harmed someone—through deception, an unpaid obligation, or an unfair arrangement—giving elsewhere does not erase the need for repair. Wisdom seeks a clean conscience and a changed practice where repair is possible.
Solomon’s warning: riches cannot carry the weight of a life
It would be incomplete to tell Solomon’s story only through his early wisdom and visible wealth. First Kings describes a later life in which abundance, power, and divided loyalties became spiritually dangerous. The king who once asked for discernment did not become immune to distraction. His resources did not guarantee that his heart would remain ordered. That is one of the Bible’s most sobering lessons about prosperity.
More money can solve a real problem, but it can also amplify existing habits. A person who avoids difficult conversations may have more ways to avoid them. A person who craves approval may have more expensive ways to seek it. A person who wants control may find that resources make control feel temporarily possible. The answer is not to fear every increase. It is to build practices that keep the heart awake: gratitude, accountability, rest, honest conversation, generosity, and limits that remain in place when income grows.
Ecclesiastes, traditionally associated with Solomon, asks readers to notice the limits of possession, achievement, and pleasure. The book does not forbid enjoying the fruit of labor. It refuses to let that fruit become the final meaning of life. This is freeing for a household that feels it must reach one more financial milestone before it can be content. A goal may be worthwhile, but it is a poor god. No portfolio, home, business, or title can replace relationship with God, love of neighbor, or a life of integrity.
A seven-day practice for wiser prosperity
Instead of pursuing a vague image of abundance, spend one week practicing discernment in small decisions:
- Day one: List the next two weeks of essential bills and income dates.
- Day two: Identify one purchase or commitment to pause for 24 hours before deciding.
- Day three: Review one recurring charge and decide whether it still serves a real purpose.
- Day four: Set aside a small amount for a foreseeable expense or emergency reserve if the budget allows.
- Day five: Read 1 Kings 3 and discuss where your household needs discernment more than speed.
- Day six: Name one person, organization, or relationship your resources could serve with wisdom.
- Day seven: Hold a brief review: What is true? What matters most? What is our next faithful step?
Small practices do not produce instant abundance. They train attention. Over time, clearer attention can reduce expensive haste, strengthen trust at home, and help a family direct resources toward what it truly values. That is a more reliable definition of prosperity than a promise that every plan will succeed.
Practical next step
Choose one decision currently connected to money—a purchase, debt payment, savings goal, job move, gift, or investment question. Before acting, write four answers: What do I know? What do I need to verify? Who will be affected? What would a patient and truthful next step look like? If the decision is significant, give yourself time and seek a qualified professional where appropriate.
For further study, read King Solomon’s 7 Principles for Household Economic Wisdom, explore Purpose-Driven Wealth, or visit the Financial Tools hub for general educational calculators.
Sources and further reading
- 1 Kings 3, 10, and 11 — Solomon’s request, wealth, and later warning
- Proverbs 13, 21, 22, and 27 — diligence, planning, debt, and careful attention
- Investor.gov — introductory investment education
- Consumer Financial Protection Bureau — budgeting tools
- Financial Consumer Agency of Canada — making a budget
Related reading
7 Wealthy Men in the Bible · Biblical Financial Wisdom Beyond Market Noise · Christian Family Legacy Planning · Tithes and Generosity
The Money North Letter
One practical money lesson. One biblical principle. One useful next step. Subscribe by email.
Educational disclaimer: This article provides general financial education and biblical reflection. It is not personalized financial, investment, tax, legal, credit, banking, or insurance advice. Account terms, laws, programs, and consumer protections vary by location and may change.